What’s Happening?
All news below is color-coded as “good“, “bad“, or “neutral” for mortgage rates.
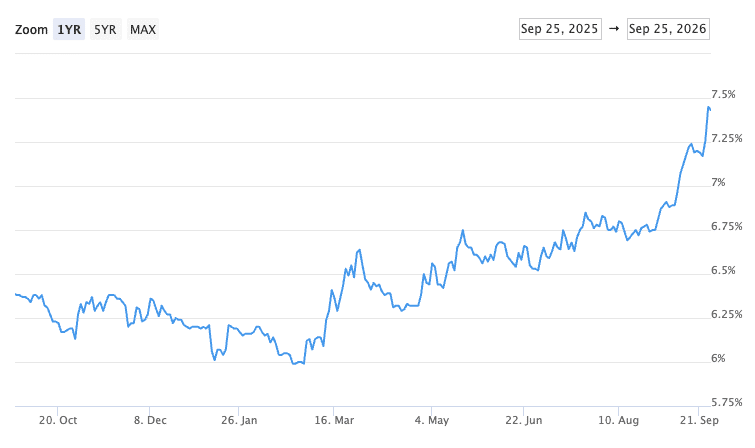
Summary: September was brutal for rates. Bad became worse as long-dated US bonds spiked again and mortgage rates did as well.
•Geopolitics (bad for rates): The war with Iran oscillates from neutral headlines to bad headlines. In September we saw news of escalation, Iranian strikes on US aircraft in Jordan, and even an attack on the East-West Saudi pipeline. The increased escalation disrupts oil supply and drives price increases.
•Brent Crude Oil Prices (bad for rates): A Barrel of Brent Crude is back up to $104, up from $90/barrell at the end of August.
•Federal Reserve Rate Hike (bad for rates): The Federal Reserve hiked rates by 0.25% this month; their target rate is now 3.75% – 4.00% (the Fed targets a range, not an exact rate). This was the first hike in over 3 years and here is some recent Fed rate history: during COVID, the Fed had an emergency meeting to cut its funds rate to near 0% and held it there for almost 2 years, from April 2020 through February 2022. Low rates and stimmy checks created massive inflation, hitting 9% by the official numbers (possibly more in the “real world”), and the Fed was forced to hike rates over an 18-month period, from February 2022 through August 2023, hiking from 0% – 0.25% to 5.25% – 5.50%. Inflation falling to sub-3% (not deflation, just slower price increases) allowed the Fed to start cutting again, very slowly, over the last 2 years, cutting by 1.75% in total. This week marked their 1st hike since June 2023.
Markets expect another 0.25% rate hike in late October, and one more 0.25% hike by late January. Total expected rate hikes over the next 12 months are 1%
•US Bond Market (bad for rates): Long-dated (10-30 year) US Treasury Bonds surged in August by about 0.125%. The 10-year broke 4.75%, a significant move at the time. September dwarfed August, rising 0.375%, with the 10-Year Treasury yield rocketing through 5%, considered an inflection point, and now holding above 5.1% for the last week of September. Surging bond yields are a massive tailwind for rising interest rates, and mortgage rates are most closely influenced by the 10-year Treasury Bond.
The US Treasury is trying to increase bond repurchases to drop rates, but it’s about as effective as pouring a bucket of water on a forest fire.
•Inflation Report (neutral for rates): The CPI report covering August showed year-over-year inflation holding at 3.4%. The CPI report is heavily driven by the price of oil, and oil is up 15% over August and September. It’s likely we’ll see a higher yearly inflation number in the September CPI report. This can contribute to higher mortgage rates.
•Jobs Report (bad for rates): 162,000 new jobs were created in August, far exceeding the forecasted 53,000. Restaurant and Bar employment growth led this report and accounted for 59,000 of the new jobs, far exceeding the average monthly growth of 12,000 jobs in this sector. Job growth exceeding expectations signals a strong economy, which can lead to rising inflation and future Federal Reserve hikes.
•Unemployment Metric (bad for rates): Unemployment is unchanged from recent months, still sitting at 4.1%. Unemployment was 4.2% in June and 4.3% in May. Falling unemployment shows labor market strength, which can push rates up, though its effect is minor compared to the other factors affecting rates these last couple of months.